Even after you stop working, having emergency liquidity is essential to protect your financial stability. Unexpected expenses like medical bills, home repairs, or income gaps can happen at any time. Without accessible funds, you might have to dip into your long-term savings or face penalties, risking your retirement plans. Keeping your emergency reserve separate and strategic guarantees peace of mind and control. To discover more about maintaining critical liquidity in retirement, keep exploring these key strategies.

Get home office essentials delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Key Takeaways
- Retirement emergencies can arise unexpectedly, requiring immediate access to funds without disrupting long-term savings.
- Maintaining liquidity prevents the need to prematurely withdraw from retirement accounts, avoiding penalties and reduced growth.
- Emergency funds provide peace of mind and financial independence during unforeseen medical, housing, or income-related expenses.
- Proper liquidity management safeguards wealth and ensures quick access to cash when legal or regulatory issues arise.
- Continued emergency liquidity supports overall retirement resilience, allowing focus on enjoyment rather than financial stress.
In today’s financial landscape, emergency liquidity remains a critical safety net that can prevent crises from spiraling out of control. Even after you stop working, unexpected expenses can still arise—medical emergencies, home repairs, or sudden changes in your income. Maintaining accessible funds ensures you’re prepared for these surprises without derailing your retirement planning or forcing you into unfavorable financial decisions. Proper emergency fund management becomes especially essential once you’re no longer earning a regular paycheck, as it sustains your financial independence and peace of mind.
Maintaining accessible funds is vital to protect your retirement from unexpected expenses and preserve your financial independence.
You might think that once you’re retired or semi-retired, your financial security is set. However, neglecting emergency liquidity can leave you vulnerable. Your savings, investments, and pension income form the backbone of your retirement plan, but they’re not always liquid or easily accessible in a pinch. Having a dedicated emergency fund ensures you can cover immediate costs without dipping into your long-term retirement savings, which are typically less flexible and may incur penalties if accessed prematurely. This separation helps you protect the growth of your wealth while ensuring liquidity when you need it most. Incorporating financial resilience into your planning can further enhance your ability to adapt to unexpected financial challenges.
Effective emergency fund management involves balancing accessibility with safety. You want your emergency funds to be readily available, but also secure enough that they won’t lose substantial value over time. Many retirees opt for high-yield savings accounts, money market funds, or short-term certificates of deposit. These options provide quick access and preserve your capital, giving you confidence that funds will be there when necessary. You shouldn’t keep the entire nest egg in cash—diversification and strategic allocation are key—but a sufficient cash reserve can greatly reduce stress during financial hiccups. Understanding how to manage liquidity effectively can be vital in optimizing your emergency funds. Additionally, being aware of the laws and regulations that impact your access to funds can help you make more informed decisions about where to keep your emergency reserves. Staying informed about liquidity options and legal considerations ensures your funds remain both accessible and protected.
Retirement planning isn’t just about accumulating assets; it’s about safeguarding your lifestyle against uncertainties. Having an emergency liquidity cushion enables you to focus on enjoying your retirement rather than constantly worrying about what-if scenarios. It also provides flexibility, allowing you to handle unforeseen expenses without compromising your long-term financial goals. In essence, emergency fund management is a proactive step that complements your broader retirement strategy, ensuring you’re prepared for life’s unpredictable moments.
Ultimately, your emergency liquidity gives you control. It’s a tangible safety net that empowers you to face unexpected challenges confidently, without sacrificing your financial stability. Staying vigilant about maintaining and managing your emergency funds keeps your retirement secure, ensuring that your hard-earned savings work for you—not against you—when you need them most. Additionally, understanding the importance of biodiversity and sustainable practices can serve as a reminder of the value of resilience and adaptability in all areas of life, including financial planning.
Frequently Asked Questions
How Much Emergency Liquidity Should Retirees Maintain?
You should maintain enough emergency liquidity to cover three to six months of living expenses, ensuring your Retirement savings and investment strategies stay intact during unexpected events. This buffer helps you avoid dipping into your investments during market downturns, protecting your long-term goals. Regularly review your emergency fund, adjusting it based on changes in your expenses or income, so you stay prepared for life’s surprises without compromising your financial security.
What Are the Best Sources for Emergency Funds After Retirement?
You should consider accessible options like savings accounts, money market funds, and short-term CDs for emergency funds after retirement. These sources offer quick access and safety. An interesting statistic shows that nearly 40% of retirees face unexpected expenses annually. When choosing investment strategies, be mindful of tax implications, as certain accounts like Roth IRAs can provide tax-free withdrawals, helping you preserve your emergency funds while minimizing taxes.
How Often Should Retirees Review Their Emergency Liquidity Plan?
You should review your emergency liquidity plan at least annually, or more often if your financial situation changes. Regular reviews guarantee your investment diversification remains aligned with your needs, and your estate planning stays current. Life events or market fluctuations can impact your funds, so staying proactive helps you maintain access to emergency cash and avoid unnecessary stress during unforeseen events.
Can Emergency Liquidity Help Cover Healthcare Expenses?
Emergency liquidity can definitely help cover healthcare expenses, especially during medical emergencies or unexpected expenses. When sudden health issues arise, having quick access to cash means you won’t be forced to make tough choices or delay essential care. It acts as a safety net, giving you peace of mind and financial stability. In retirement, this readiness becomes even more critical, ensuring you focus on recovery rather than financial stress.
What Are Common Mistakes in Managing Post-Retirement Emergency Funds?
You might fall into common pitfalls by mismanaging post-retirement emergency funds. Avoid risky investment strategies that could jeopardize your liquidity, and consider the tax implications of withdrawing funds. Keep your emergency fund in accessible, low-risk accounts, and plan withdrawals carefully. By staying aware of your investment choices and tax effects, you guarantee your emergency fund remains reliable, providing peace of mind during unexpected expenses.
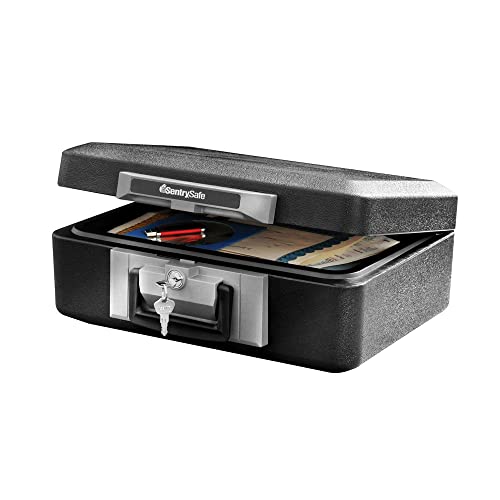
SentrySafe Fireproof Safe Box with Key Lock, Chest Safe with Carrying Handle to Secure Money, Jewelry, Documents, 0.25 Cubic Feet, 6.3 x 15.3 x 12.1 Inches, 1160
- Fireproof and Fire-Resistant: Protects valuables from fire up to 1550ºF
- UL and ETL Certified: Endurance and protection for documents and media
- Secure Key Lock: Privacy lock with two keys for security
As an affiliate, we earn on qualifying purchases.
Conclusion
Even after you stop working, having emergency liquidity remains vital. Imagine facing unexpected medical bills or sudden home repairs—you’ll need quick access to funds. Take the example of Sarah, who retired and overlooked her emergency fund; when her roof leaked, she struggled to cover the costs. By maintaining a steady cushion, you guarantee you’re prepared for life’s surprises, giving you peace of mind and financial stability in your golden years.
Evergreen bestsellers Picks
bestsellers
As an affiliate, we earn on qualifying purchases.